Tax Planning for You and Your Family – Part 1: Secrets to Achieving Your Financial Goals
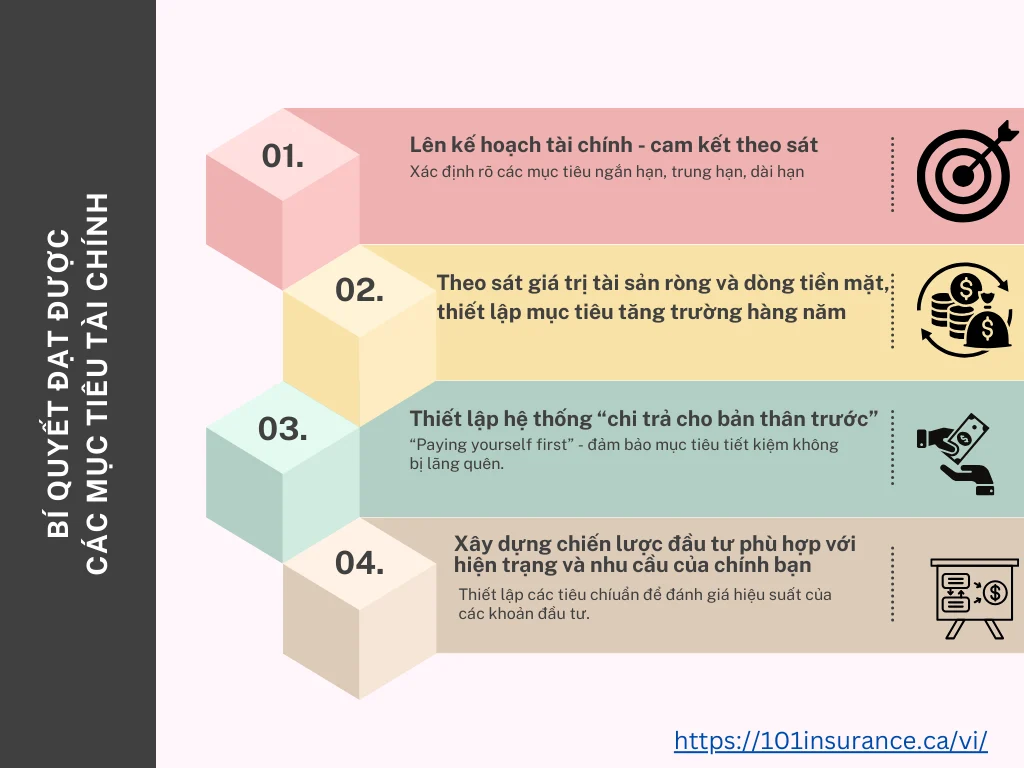
It’s been a long time since I wrote an article, hasn’t it? I’ve been making so many videos lately that I haven’t written in a while — I’m afraid my writing skills are getting rusty 😀 So, since I’m currently reading the book “Tax Planning for You and Your Family,” I’ll try to briefly write up the important points from each chapter that I think will be useful for those of you who care about financial matters. Since these articles of mine are only summaries, if you need more detail, you can find the book to read (very easy to find at libraries) or leave a comment with your questions. I’ll also try to make a few summary images so you can easily follow each chapter.
To achieve your financial goals, planning and following specific strategies is extremely important. Below are detailed steps to help you manage your finances effectively and achieve your set goals.

1. Make a Financial Plan — Commit to Following It Closely
The first step to achieving your financial goals is to build a detailed plan. This plan needs to include short-term and long-term goals, such as saving for an emergency fund, buying a home, your children’s education, and preparing for retirement. Commit to following the plan closely by regularly tracking and evaluating your progress, adjusting when necessary to ensure you always stay on the right track.
Financial plans should be clearly divided into short-term goals (under 5 years), medium-term goals (5-10 years), and long-term goals (over 10 years), because the choice of investment tools and risk management methods will also depend a great deal on these plans.
2. Track Your Net Worth and Cash Flow, and Set Annual Growth Targets
Tracking your net worth (the total value of your assets minus your liabilities) and your cash flow (the difference between income and spending) is the best way to clearly understand your financial situation. Setting annual growth targets gives you motivation and a concrete plan to increase your net worth and cash flow.
Remember, to increase your net worth, don’t just focus entirely on increasing your income and forget about managing your spending and saving. There are quite a few cases of families whose income went up but whose monthly surplus still didn’t increase, for exactly this reason.
3. Set Up a “Pay Yourself First” System
The “pay yourself first” system means you prioritize saving and investing before spending on other needs. This way, you will always ensure that a portion of your income is set aside for important financial goals. Automate this process by setting up automatic savings or investment contributions at the beginning of each month from your bank account (TFSA or RRSP). Your savings level should be at least 10% of your total income.
4. Build an Investment Strategy That Suits Your Own Situation and Needs
Everyone has a different financial situation and goals, so your investment strategy needs to suit your personal circumstances and needs. Research and choose investment channels such as stocks, bonds, investment funds, and real estate to build a diversified investment portfolio. Make sure your investment strategy is adjusted over time to respond to changes in your finances and goals.

5. Contribute the Maximum $2,500/Year to an RESP to Receive an Extra 20% Grant from the Government
The Registered Education Savings Plan (RESP) is a useful tool for saving for your children’s education. When you contribute the maximum $2,500 per year to an RESP, you will receive an extra 20% grant from the government, up to a maximum of $500 per year. This helps your savings grow quickly and effectively. Because the growth in value inside the RESP account will be taxed in the child’s hands when this money is used for education purposes, the tax payable on this growth in assets will be very low and could be zero at a time when the child has no other source of income.
6. Encourage Your Children to Invest the Money They Earn from an Early Age
Educating and encouraging your children to invest early is a good way to help them develop financial management skills. Explain to your children the importance of saving and investing, as well as how investment channels work. Encourage your children to use the money they earn from small jobs or lucky money (tiền mừng tuổi) to invest and accumulate assets.
7. Consider Using Your RRSP as a Down Payment When Buying Your First Home Under the Home Buyer’s Plan
The Home Buyer’s Plan allows you to withdraw up to $35,000 from your Registered Retirement Savings Plan (RRSP) account to use as a down payment when buying your first home without having to pay tax. This helps you save that tax money and easily own your dream home.
8. Increase Your Mortgage Payment Frequency to Reduce Interest Costs
An effective way to reduce your overall interest costs and shorten your mortgage repayment time is to increase your payment frequency. Instead of paying monthly, you can switch to paying weekly or every two weeks. This helps reduce the amount of interest you have to pay and pay off the debt quickly.

9. Plan to Minimize Capital Gains Tax from Selling a Vacation Home
If you intend to sell a vacation home, look into measures to minimize capital gains tax to optimize the profit from selling the home. This can include using tax deductions, considering the timing of the sale, and other asset management strategies.
10. Set Up an Emergency Reserve Fund or a Line of Credit
An emergency reserve fund or a Line of Credit account is essential for dealing with emergency financial situations such as losing your job, unexpected medical expenses, or other incidents. Set a goal of saving from 3 to 6 months of living expenses in your emergency fund to reduce financial pressure when unexpected events occur.
11. Make Sure You Have Life Insurance / Critical Illness Insurance That Meets Your Financial Needs, and Prepare an Updated Will
Life insurance and critical illness insurance are important tools to protect your finances and your family’s in case a risk occurs. Make sure you have enough insurance to cover living expenses, medical expenses, and debts if you are no longer able to work.
In addition, update your will to ensure your assets are divided according to your wishes and to protect your loved ones’ rights and interests. Preparing a will in advance not only helps you ensure your assets are arranged according to your wishes, but also saves you the amount called the probate fee — the cost that arises based on a % of the total value of your assets when they have to go through the probate process (the procedure for validating a will) if you haven’t prepared a will in advance.12. Consider a Power of Attorney
A Power of Attorney allows you to designate someone else to manage your assets and make financial decisions on your behalf in case you are no longer able to decide for yourself. This helps protect your assets and ensures financial decisions are carried out according to your wishes.
I’ll stop Part 1 here. In the next part — Part 2 — I’ll continue this series with the topic: “Advice on claiming tax deductions and tax credits.”
Sarah Do
Travel, Life, and Health Insurance Advisor.
Related Articles
Term vs Permanent Life Insurance in Canada: Which One Should You Choose?
Comparing Term and Permanent Life Insurance in Canada: benefits, costs, pros and cons, and tips for choosing the right insurance for your family.
$500,000 of insurance sounds like a lot — until you sit down and do the math
$500,000 of insurance sounds like a lot, but after paying off the mortgage, replacing income and setting money aside for the children's education, how much would the family have left? Let's work through an example to see whether this amount of insurance is really enough.
How Much Life Insurance Is Enough for a Family in Canada?
How much life insurance is enough: $250,000, $500,000 or $1 million? There is no single number that fits every family in Canada. Learn how to calculate your Insurance Needs based on your mortgage, debts, income that needs to be replaced, childcare costs and existing assets, so you can choose the right amount of coverage for your family.