How Much Life Insurance Is Enough for a Family in Canada?
Table of Contents

This is usually one of the first questions when you start thinking about buying life insurance:
Should I buy $250,000, $500,000 or $1 million?
It sounds quite arbitrary. And honestly, it is.
There is no one right number for everyone.
Many clients call me and are very decisive:
“Please send me a quote for $100,000 of coverage!”
The question I usually ask right after that is:
“Why did you choose $100,000?”
And the truth is, very few people really know how much they need. Most of us choose a number because it feels like it “seems enough”, or because we heard someone else bought about that much.
So how much is actually enough?
In fact, answering this question is not as complicated as you might think.
Let’s start with a simple question:
“If I were to suddenly pass away one day, how much money would my family need to carry on with life?”
From that question, we can start calculating.
1. What is life insurance really for?
Many people think of it quite simply: life insurance is to leave a really large lump sum of money for their family when they die.
But the more important purpose of life insurance is to replace the financial value that the insured person can no longer provide when they pass away.
Those needs are usually divided into two groups.
1.1. Immediate needs
- Final expenses
The funeral and the expenses that arise right after a person passes away.
- Debts
For example, personal debts, a line of credit, credit cards, a car loan…
- Mortgage
A mortgage is also a debt, but it is usually the biggest debt in a family’s lifetime. 😊
You can ask yourself:
“If I died tomorrow, would I want the person left behind to have to keep carrying the entire mortgage?”
However, not every family needs to buy enough insurance to pay off the mortgage completely.
For example, if the surviving spouse still has a good income, your goal might simply be to reduce the mortgage to a level they can comfortably keep paying.
1.2. The family’s future needs
This is the part that is easy to overlook.
- Childcare costs
If the family loses a caregiver, will additional costs arise?
It could be daycare, before/after-school care, summer camps, someone to drive the children around, or other care costs.
And remember:
The younger the children, the longer the family will need financial support.
A family with children aged 2 and 5 will have very different needs from a family with children aged 17 and 20.
- Education costs
If you were no longer here, how much would you still want to contribute to your children’s education?
This item is sometimes quite easy to overlook.
Personally, I place a lot of importance on my children having the financial means to study after high school. That is why, when I calculate coverage for myself, I always set aside an expected amount so that my children can complete at least four years of university.
Every family will have a different goal. What matters is that you identify what your goal is.
- Family living expenses
This is usually one of the biggest items.
If your income disappeared, would your family need to replace all of that money?
Not necessarily.
Some of your expenses would also go away. But the mortgage or rent, groceries, utilities, childcare and many other child-raising costs continue.
For example, after calculating, you find that the family needs about an extra $40,000 each year to maintain their current life for 10 years.
This item alone is already:
$40,000 × 10 years = $400,000
This is only a simple calculation, not yet accounting for factors such as investment returns, inflation or taxes.
If you do not want to calculate in detail, people sometimes use about 5–10 times annual income as a quick way to estimate.
But this is only a rule of thumb. A family with two young children and a large mortgage is clearly different from a family with no children that has almost paid off the house.
In addition, you can also add other financial goals that you still want your family to be able to achieve, or simply an extra amount that you hope to leave for the people you love.
2. A simple formula to estimate your insurance needs
After identifying the needs above, you can use a fairly simple formula:
Insurance Need = Debts + The family’s future needs + Income to be replaced − Existing assets − Existing insurance
“Debts” can include the mortgage if your goal is to pay off or reduce that loan.
After adding up what the family needs, subtract the financial resources the family already has, for example:
- Savings
- Non-registered investments
- TFSA
- Existing life insurance
- Group life insurance from your employer
But there is one point to keep in mind:
Not every asset you have should automatically be spent if you pass away.
For example, an RRSP set aside for the surviving spouse’s retirement may not be an amount the family wants to withdraw to pay off the mortgage.
So, when subtracting existing assets, ask yourself:
“Do I really want my family to use this money for that purpose?”
Of course, when I do a needs analysis for clients, I do not sit there manually adding and subtracting each item like this. I have tools to calculate in more detail.
If you would like to calculate it yourself first, just message me. I can send you a file to fill in and try yourself. And if you would like me to do the calculation with you, you can book an appointment with me.
3. Don’t forget the value of the person who does not earn an income
This is a point that is very easy to overlook.
Suppose one person stays home to care for the children and currently has an income of $0.
Does that person not need life insurance?
Try thinking about what would happen if that person were no longer here:
- Who will care for the children?
- Will the family have to pay for more daycare?
- Who will drive the children to and from school?
- Who will cook and clean?
- Will the surviving spouse have to reduce their working hours to care for the family?
All of that work has economic value, even though it does not produce a monthly paycheque.
Therefore:
An income of $0 does not mean a financial value to the family of $0.
4. When should you recalculate your Insurance Needs?
Life insurance is not something you buy and then forget about for 20 years.
Our insurance needs change as our lives change.
You should review your coverage when there are major changes such as:
Getting married → Having children → Buying a home → Income changes → Taking on more mortgage → Separation/divorce → Children growing up → Significant changes in assets
A policy that suited you at age 30 may not necessarily still suit you at age 40.
So in the end, is $500,000 or $1 million enough?
The answer is still:
It depends on your family.
$500,000 may be more than necessary for one person, while $1 million may still not be enough for another.
So instead of starting with the question:
“How large a policy should I buy?”
Try asking:
“If my income and my contributions disappeared tomorrow, what do I want my family to still be able to do?”
If you do not know whether your current coverage is lacking, enough, or more than enough, start with a needs analysis.
List your debts, your mortgage, your children’s needs, the income that needs to be replaced, and the assets and insurance you already have.
From there, you will know how much you truly need to protect — before thinking about which product to buy.
If needed, I can do this calculation together with you based on your family’s real circumstances. Or if you just want to try calculating it yourself first, message me for the Insurance Needs Calculator file.
Disclaimer: This article is for general information purposes only and does not replace financial, tax or legal advice suited to your personal circumstances.
Related Articles
Term vs Permanent Life Insurance in Canada: Which One Should You Choose?
Comparing Term and Permanent Life Insurance in Canada: benefits, costs, pros and cons, and tips for choosing the right insurance for your family.
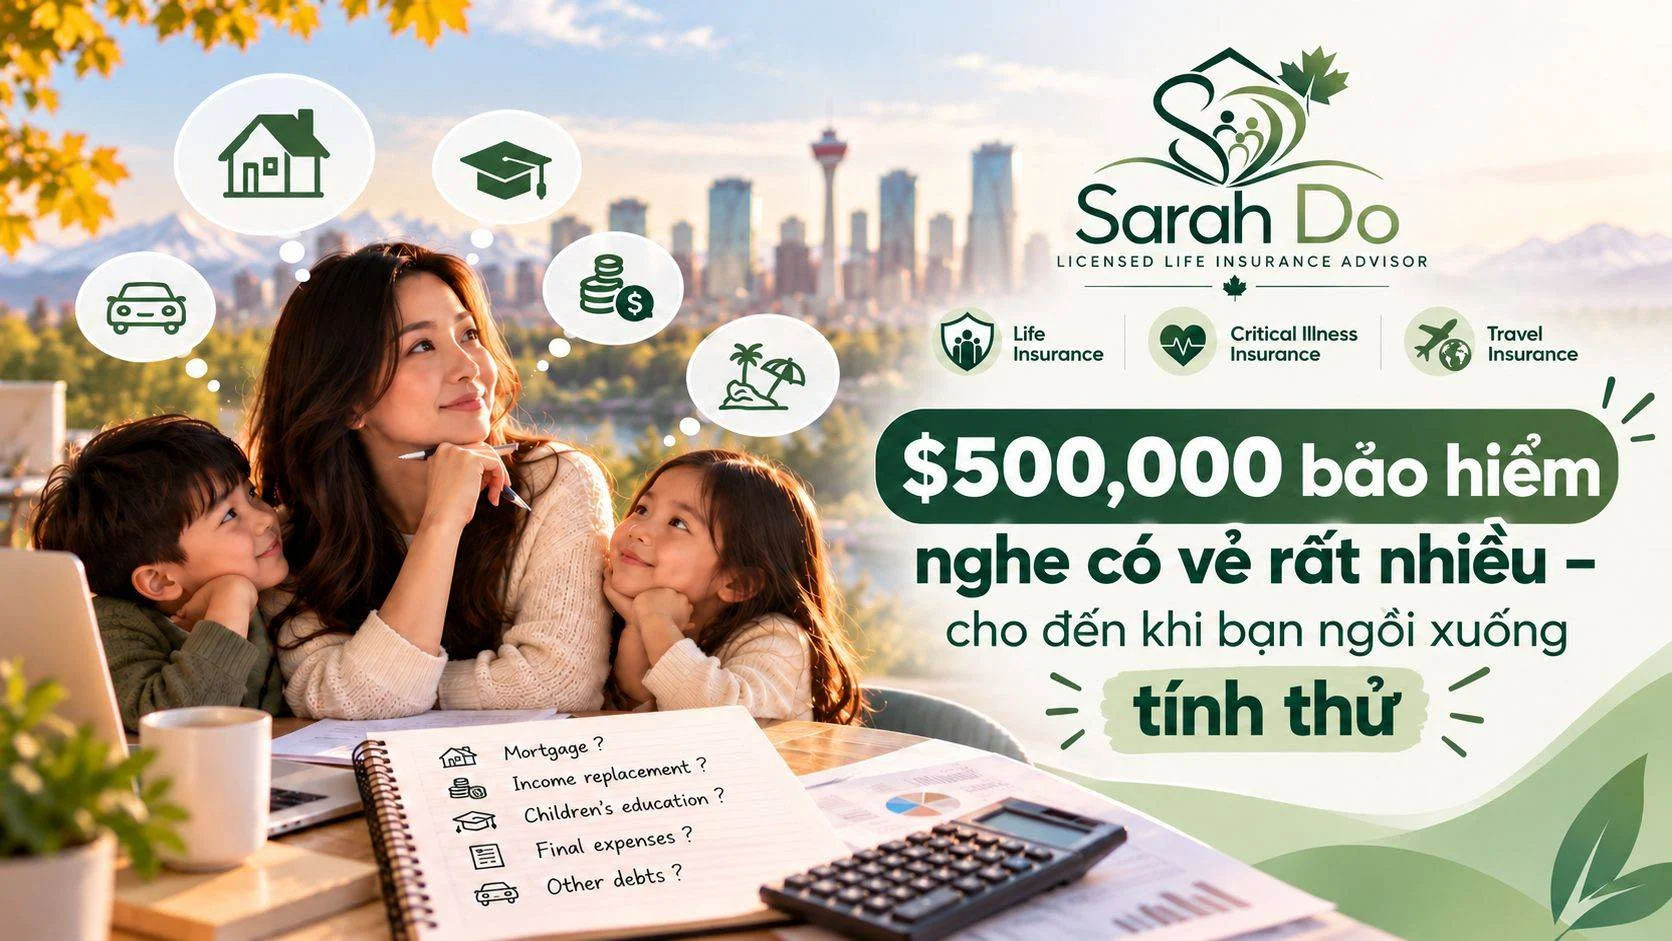
$500,000 of insurance sounds like a lot — until you sit down and do the math
$500,000 of insurance sounds like a lot, but after paying off the mortgage, replacing income and setting money aside for the children's education, how much would the family have left? Let's work through an example to see whether this amount of insurance is really enough.
Optimizing Taxes in Retirement with Permanent Life Insurance – A Smart Financial Solution
Optimizing retirement income with permanent life insurance – A financial solution that helps reduce personal income tax, create passive income and protect assets for the next generation!